
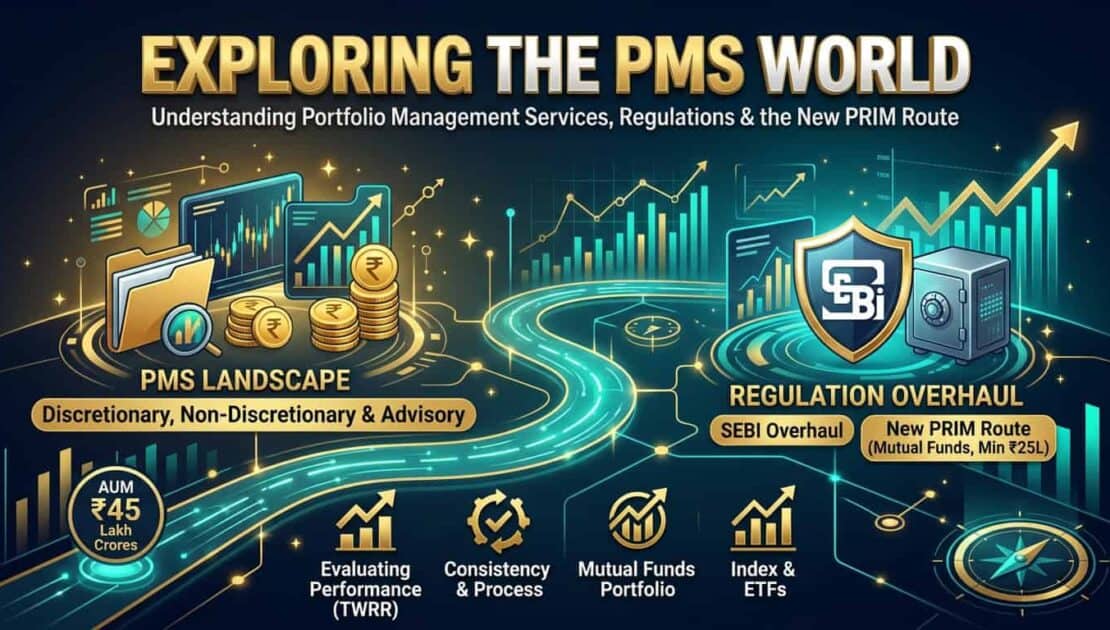
Exploring the PMS World
- October 13, 2026
- Posted by: Arunanjali Securities
- Category: Business
No Comments
Overhaul of PMS regulations Over the last couple of years, the regulatory direction has emerged increasingly clearly. SEBI, RBI and the Government are tweaking and tightening in tandem, rules and regulations relating to trading and its financing and taxation to contain speculative excesses and the concomitant losses incurred by the overwhelming majority of retail traders…
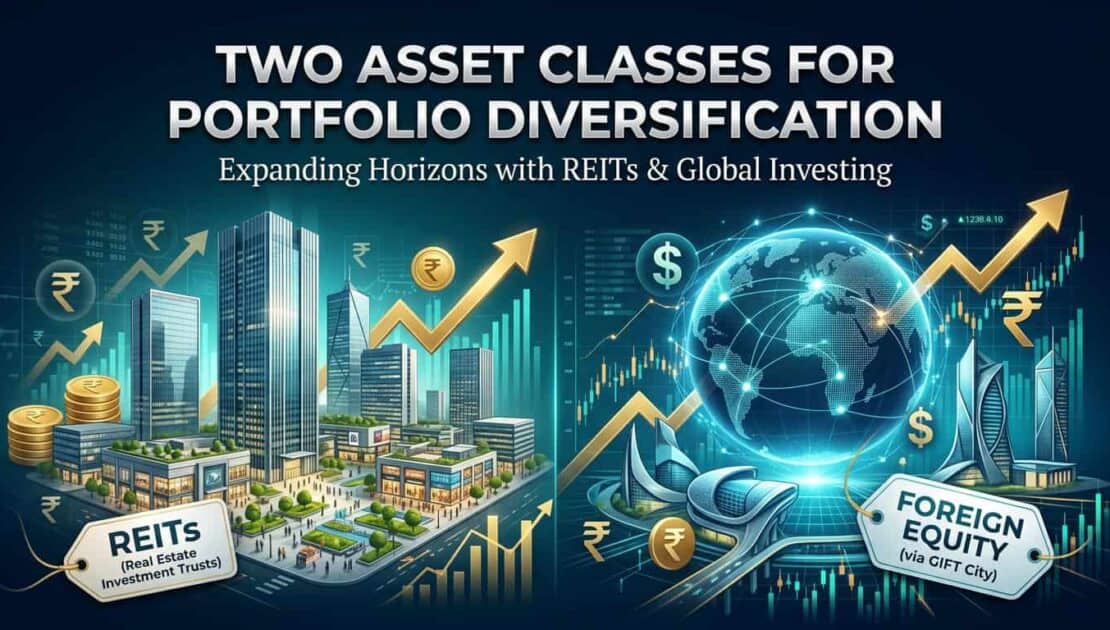
Two Asset Classes for Portfolio Diversification
- September 15, 2026
- Posted by: Arunanjali Securities
- Category: Business
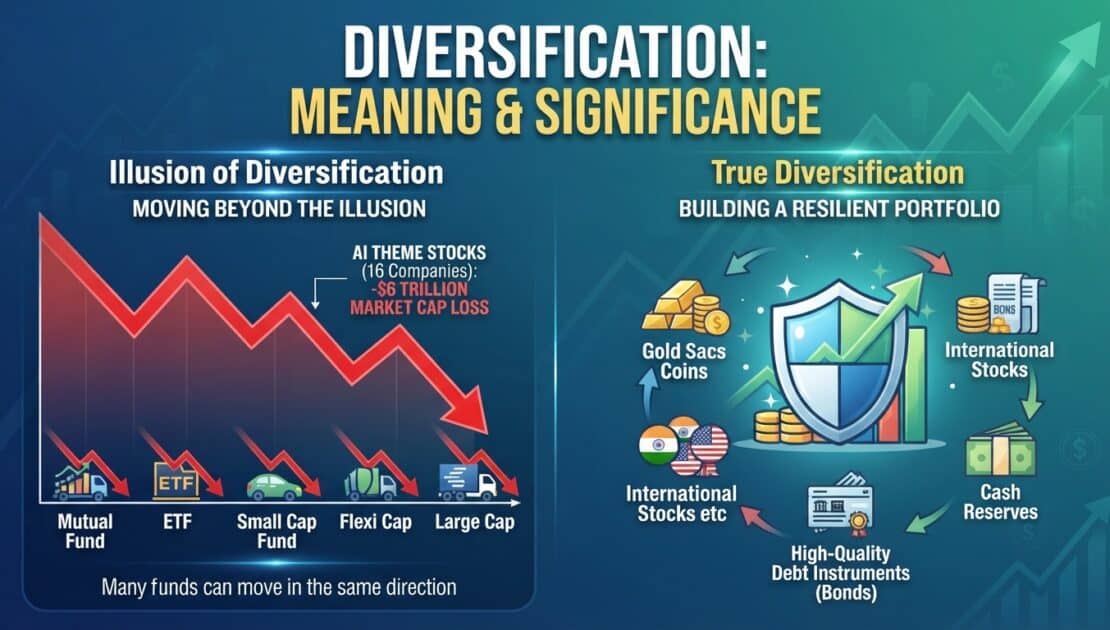
August edition of Points to Ponder sought to explain how variety could be mistaken for diversity and that effective diversification would have to ensure that constituent asset classes of an investment portfolio do not all move in the same direction in all situations. There are, of course, considerations of investor’s risk profile and his goals…
Diversification – Meaning & Significance
- September 14, 2026
- Posted by: Arunanjali Securities
- Category: Business
In the June 26 edition of Points to Ponder, it was suggested that FIIs were rushing out of Indian stock markets to chase markets that were in the forefront of AI Induced capex super-cycle. Yet there have been assertions that India with its well diversified market, was offering a contrarian bet. The unfolding AI rout…
Semiconductors & Data Centres in AI Ecosystem
- September 14, 2026
- Posted by: Arunanjali Securities
- Category: Business
There is no denying the fact that for some time now, money is chasing economies where AI induced capex super cycle is holding sway. Whatever may be our apprehensions regarding AI, we live in a world where AI matters, because AI will increasingly shape economic activity, public services, defence capabilities and access to knowledge. True…
The Unending Churn in the Markets
- June 15, 2026
- Posted by: Arunanjali Securities
- Category: Business
If one were to read Adil Rustomjee’s delightful book, Running Behind Lakshmi, which covers the journey of capital markets in India for over a century, one would conclude that change is the only constant in the capital markets. Over the last five years the pace of change has accelerated even more. From $ 3.1 trillion…
Citrini Apocalypse; Any Escape?
- May 24, 2026
- Posted by: Arunanjali Securities
- Category: Business
Points to Ponder, May 2026 Although the Citrini report makes a timely and cogent case of how the advent of AI agentic tools would destroy jobs and cause the death of intermediation, a deeper analysis of the same reveals some flaws. An important issue that Citrini seems to have glossed over is the crucial fact…
Citrini; Drumming Up Doom or a Timely Alert?
- April 15, 2026
- Posted by: Arunanjali Securities
- Category: Business
Points to Ponder, April 2026. Throughout recorded history so far, every single advance in technology, enhanced and supplemented human ability to achieve objectives determined by him. But for the first time, over the last four years or so, Artificial Intelligence (AI), the unravelling of which, is making it increasingly clear that AI, which initially will …
Budget 2026-27
- March 31, 2026
- Posted by: Arunanjali Securities
- Category: Business
Little was expected of the budget this year. Corporate and personal income tax rates were reduced in the earlier budgets and reduction and rationalization of GST rates took place during the year but well before the budget. Moreover, it was a budget that faced quite a few constraints by way slackening tax revenues, sluggish private…
IPO Frenzy – Three Day Circus Or, Sign of a Mature Market?
- February 17, 2026
- Posted by: Arunanjali Securities
- Category: Business
The last couple of years have witnessed record level of IPOs both in terms of numbers and aggregate funds raised. Fundraising through mainboard IPOs surged from ₹67,562 crore in FY 2023 to a record ₹1,82,460 crore in FY 2024, an increase of over 170%. Calendar year 2025 further saw approximately ₹1.95 lac crores raised across 373 issues, including both mainboard and…
Indian Markets in the Global Pecking Order
- January 10, 2026
- Posted by: Arunanjali Securities
- Category: Business
The rupee is wilting under weight of the ballooning trade deficit and the persistent pull out by FPIs which has exceeded Rs 80000 crores so far this year. FPI holding of Indian equities has come down from 20% in 2017 to about 17% now. However, consistent inflows into mutual funds (MFs) have been holding up…